Managing money is not always as simple as earning, spending, and saving. Between monthly bills, shopping expenses, loan payments, savings goals, and investments, it can be difficult to understand exactly where your money goes. Even people with a regular income sometimes struggle to keep their finances organised.
This is where finance tools can make a real difference.
In 2026, digital finance tools are making personal money management more accessible. From budgeting apps and expense trackers to investment dashboards and loan calculators, these tools help people organise financial information and make more informed decisions. Instead of maintaining everything in notebooks or complicated spreadsheets, users can explore convenient digital options that bring important financial details together.
However, not every finance tool serves the same purpose. Some help track daily spending, while others focus on long-term investments, tax preparation, debt repayment, or financial planning. Choosing the right one depends on your financial situation and what you want to achieve.
In this guide, we explore the best types of finance tools to consider in 2026, how they work, their benefits, and what to look for before using them.
What Are Finance Tools?
Finance tools are digital applications, websites, calculators, or software programs that help individuals and businesses manage financial activities.
They can make it easier to track income, monitor expenses, prepare budgets, calculate loan payments, review investments, and plan savings goals.
For example, someone who wants to save money for a holiday can use a budgeting tool to set a monthly spending limit and monitor progress. A person considering a personal loan can use an EMI calculator to estimate monthly repayments before applying.
Finance tools are useful because they turn financial information into something easier to understand. Rather than making decisions based on guesswork, users can review figures, compare options, and plan ahead.
Why Are Finance Tools Important in 2026?
Financial management has become increasingly digital. People use online banking, digital payment services, investment platforms, and mobile applications to handle everyday transactions. Having a clear view of these activities can help prevent confusion and improve financial planning.
Here are some reasons finance tools are becoming valuable in 2026.
1. Better Control Over Everyday Spending
Small purchases can add up quickly. Coffee, food delivery, subscriptions, shopping, and transportation expenses may seem manageable individually, but together they can take up a considerable part of a monthly income.
Expense-tracking tools help users understand where their money is going. By reviewing spending categories, people can identify habits that may need attention.
2. Easier Budget Planning
A budget gives every part of your income a purpose. Finance tools make it easier to divide money between household expenses, savings, loan payments, and personal spending.
Some applications also provide reminders or alerts when spending approaches a selected limit.
3. More Organised Financial Goals
Whether someone wants to build an emergency fund, purchase a home, or save for education, financial goals require consistency.
Goal-tracking tools can help users set a target amount, choose a timeline, and monitor their progress.
4. Convenient Financial Calculations
Calculators can simplify decisions involving loans, savings, investments, and interest rates. They help users understand estimated costs without manually working through complicated formulas.
5. Improved Financial Awareness
Regularly reviewing financial information can help people recognise spending patterns, understand their obligations, and make more thoughtful decisions.
Best Finance Tools to Consider in 2026
The right finance tool depends on the task you want to manage. Here are some useful categories and examples worth exploring.
1. Budgeting Tools
Budgeting tools help users plan how their income will be used during a particular period. They are especially useful for people who want to control unnecessary spending and build consistent savings habits.
Most budgeting applications allow users to create spending categories such as groceries, rent, transportation, entertainment, and savings.
Some popular options include:
These tools can be useful for individuals, couples, and families who want a clearer picture of their monthly finances. Features, prices, and account-linking availability vary by region.
2. Expense Tracking Tools
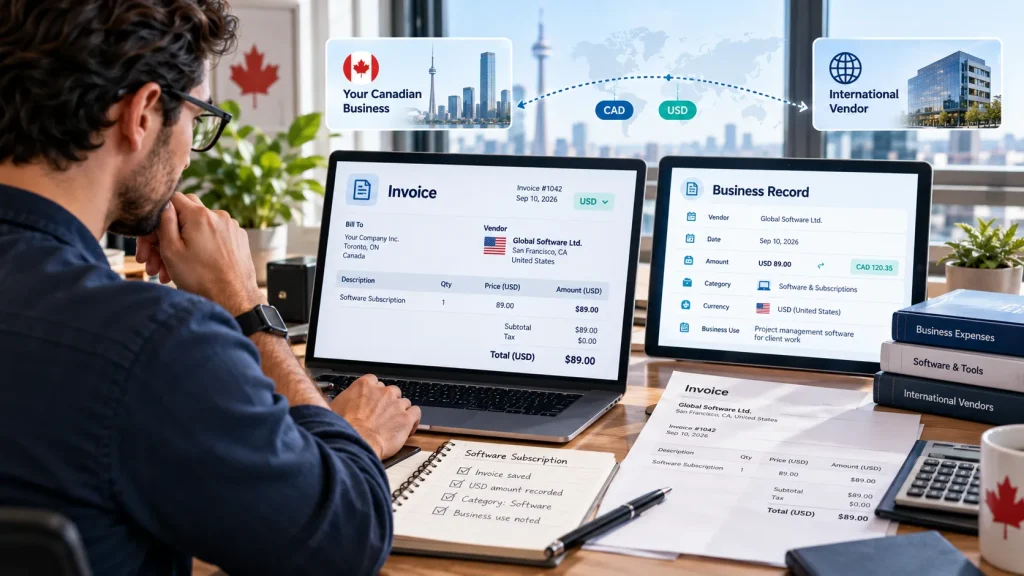
An expense tracker records and categorises money after it has been spent. It helps users understand their actual spending habits rather than relying on memory.
For example, someone may believe that most of their monthly income goes towards rent and groceries. After reviewing an expense report, they might discover that online shopping, subscriptions, or food delivery account for a larger share than expected.
Useful expense-tracking options include:
Some applications require manual transaction entries, while others offer account connections or automated categorisation. Users should check exactly what information an app accesses before connecting financial accounts.
3. Personal Loan and EMI Calculators
Loan calculators are helpful for anyone considering borrowing money. They estimate monthly repayments based on the loan amount, interest rate, and repayment period.
A personal loan EMI calculator, for example, can help someone compare different borrowing amounts and repayment tenures before choosing a loan.
Common calculator options include:
- Personal loan EMI calculator.
- Home loan EMI calculator.
- Car loan EMI calculator.
- Loan interest calculator.
- Loan eligibility calculator.
These tools can help users understand the possible cost of borrowing. However, the final repayment amount may differ depending on lender fees, processing charges, interest calculation methods, and loan conditions.
Before applying, always review the lender’s official terms and repayment schedule.
4. Savings and Goal-Planning Tools
Saving money becomes easier when there is a clear target. Savings tools help users plan for specific goals and monitor how consistently they are putting money aside.
For example, someone planning to purchase a new laptop may set a savings target of ₹60,000 over twelve months. A goal planner can help break that target into smaller monthly contributions.
Common savings goals include:
- Building an emergency fund.
- Saving for a holiday.
- Planning for education expenses.
- Preparing for a home purchase.
- Creating a retirement savings plan.
- Saving for a major personal purchase.
Some finance applications also provide recurring reminders and progress summaries. These features can encourage regular saving, although the actual results depend on income, expenses, and individual financial habits.
5. Investment Tracking Tools
Investment tracking tools help users monitor financial assets such as stocks, mutual funds, exchange-traded funds, and other supported investments.
They can display portfolio values, investment performance, asset allocation, and transaction information. This can be useful for people who have investments across multiple platforms.
Some options available to explore include:
The tools differ in the assets they support, the information they display, and the services they offer. Investment tracking does not guarantee returns or determine whether an investment is suitable for a particular person. <Cite refs={[“turn195083search0″,”turn195083search10”]}/>
6. Tax Preparation Tools
Tax preparation can feel complicated, particularly when someone has multiple income sources, investments, deductions, or financial documents to organise.
Tax tools can help users collect information, calculate figures, prepare returns, and understand filing requirements.
Tax-related tools may help with:
- Organising income details.
- Estimating tax liability.
- Preparing tax documents.
- Understanding eligible deductions.
- Tracking filing progress.
- Reviewing information before submission.
Tax rules and filing requirements can change. Users should confirm the applicable financial year, eligibility conditions, and official requirements before submitting a return.
7. Debt Management Tools
Managing multiple debts can become challenging when different lenders have different interest rates, repayment dates, and outstanding balances.
Debt management tools help users organise this information and create a repayment plan.
Some useful features include:
- Listing outstanding loans and credit card balances.
- Recording interest rates and minimum payments.
- Setting payment reminders.
- Estimating repayment timelines.
- Comparing debt repayment strategies.
- Monitoring progress as balances decrease.
Two commonly discussed repayment approaches are the debt snowball method and the debt avalanche method.
The snowball method focuses on paying off the smallest balance first, while the avalanche method prioritises debts with the highest interest rates. Both approaches require consistent payments and a realistic budget.
A debt calculator can help compare estimated repayment scenarios, but users should also consider fees, prepayment conditions, and lender policies.
8. Financial Planning Spreadsheets
Not every finance tool needs to be a specialised application. A spreadsheet can be an affordable and flexible way to organise personal finances.
Users can create their own tables to record income, expenses, savings, debts, and financial goals.
A personal finance spreadsheet might include:
| Financial Category | Information to Record |
|---|---|
| Monthly income | Salary and additional earnings |
| Fixed expenses | Rent, bills, and loan payments |
| Variable expenses | Food, shopping, and transportation |
| Savings | Monthly contributions and balances |
| Debt | Outstanding balances and repayments |
| Financial goals | Target amount and deadline |
Spreadsheets are particularly useful for people who prefer manual control over their financial records. However, entries need to be updated regularly to keep the information accurate.
With so many applications and websites available, choosing one can feel confusing. The best approach is to begin with your financial needs rather than downloading several tools at once.
How to Choose the Right Finance Tool
Here are some important factors to consider.
1. Identify Your Main Financial Goal
Start by asking what you want to achieve.
If your main concern is overspending, an expense tracker may be enough. If you want to plan monthly income, consider a budgeting tool. If you need to monitor investments, look for a dedicated portfolio tracker.
Choosing a tool with a clear purpose makes it easier to use consistently.
2. Check the Cost
Some finance tools offer free versions, while others charge monthly or annual subscription fees.
Before signing up, compare the available plans and check whether important features require payment. Also look for additional charges related to premium services, transactions, or financial products.
3. Review Security and Privacy
Financial information is sensitive. Before using an application, understand what data it collects, how it stores information, and whether it connects to bank accounts or other financial services.
Use strong passwords, enable additional account protection where available, and avoid sharing confidential information unnecessarily.
4. Look for an Easy-to-Use Interface
A finance tool should make money management simpler, not more complicated.
Look for clear dashboards, understandable reports, useful reminders, and straightforward navigation. If an application feels difficult to use, you may stop updating it after a few days.
5. Check Compatibility and Availability
Not every finance tool supports every country, bank, currency, or financial institution.
For users in India, it is particularly important to check whether an application supports Indian financial accounts and services. Some international budgeting tools may have limited account connectivity outside their main markets.
6. Understand the Limitations
Automated tools can make mistakes. Transactions may be categorised incorrectly, account balances may not update immediately, and calculators may not include every charge.
Always review important information and compare it with official financial records.
Benefits of Using Finance Tools
Using suitable financial tools can improve the way people organise their money. While results depend on individual habits, these tools offer several practical advantages.
| Benefit | How It Helps |
|---|---|
| Better budgeting | Helps organise income and monthly spending. |
| Expense awareness | Shows where money is being spent. |
| Time savings | Reduces repetitive calculations and manual work. |
| Goal tracking | Makes savings targets easier to monitor. |
| Debt organisation | Keeps repayment details and due dates organised. |
| Investment visibility | Helps review supported assets in one place. |
| Financial confidence | Makes financial information easier to understand. |
The biggest advantage is visibility. When people understand their income, spending, and financial obligations, they can make decisions with greater confidence.
Common Mistakes to Avoid When Using Finance Tools
Finance applications are useful, but simply downloading one does not automatically improve financial habits. The way you use a tool matters just as much as the features it offers.
Avoid these common mistakes:
1. Using too many applications: Managing several overlapping tools can create confusion. Choose a small number that meet your actual needs.
2. Ignoring regular updates: An expense tracker is only useful when transactions and financial details are recorded accurately.
3. Sharing sensitive information carelessly: Avoid providing passwords, PINs, or confidential financial details to unverified services.
4. Trusting every calculation without checking: Confirm loan estimates, tax figures, and investment information before making important decisions.
5. Forgetting about subscription charges: Review paid plans and automatic renewals so that finance tools do not become unnecessary expenses.
6. Expecting instant financial results: A budgeting app cannot create savings on its own. Consistent decisions and realistic planning are still necessary.
Simple Ways to Manage Your Money Smarter in 2026
You do not need a complicated financial system to get started. A few practical habits can make a meaningful difference over time.
- Review your income and expenses at least once a month.
- Set a realistic spending limit for different categories.
- Build an emergency savings fund gradually.
- Keep track of loan payments and other financial commitments.
- Compare borrowing costs before taking a new loan.
- Review investment performance without reacting to every market movement.
- Cancel subscriptions you no longer use.
- Use financial calculators before making major commitments.
- Protect your financial information when using digital services.
Consistency is more important than having access to dozens of financial features. Even a simple budget that you update regularly can be more useful than an advanced application you rarely open.
The Future of Finance Tools
Finance technology is continuing to develop, and digital tools are becoming more capable of organising and analysing financial information.
Artificial intelligence is one area influencing this change. AI-powered features can help categorise transactions, summarise spending patterns, answer general financial questions, and provide budgeting suggestions.
Other developments include:
Automated financial tracking: More applications are introducing features that reduce the need for manual transaction entries.
Personalised financial insights: Digital tools may provide summaries based on spending patterns and selected financial goals.
Integrated financial dashboards: Users may increasingly be able to review supported accounts, investments, and liabilities through connected platforms.
Improved financial education: Interactive calculators and digital learning resources can make complex financial topics easier to understand.
More attention to data protection: As financial services become more connected, privacy, consent, and secure data handling will remain important considerations.
These developments may make financial management more convenient, but they do not remove the need to verify information or make independent decisions.
FAQ’s
1. What are finance tools?
Finance tools are digital applications, calculators, and software that help users manage budgets, track expenses, monitor investments, and plan savings.
2. Which finance tools are best for managing money in 2026?
Budgeting apps, expense trackers, EMI calculators, savings planners, and investment tracking tools are useful options for managing money.
3. Are finance tools useful for beginners?
Yes, finance tools can help beginners understand spending habits, create budgets, set savings goals, and organise financial information.
4. Are free finance tools available?
Yes, many finance tools offer free versions with basic features, although some advanced services may require a paid subscription.
5. How do I choose the right finance tool?
Choose a tool based on your financial goals, ease of use, security features, cost, and compatibility with your bank or financial accounts.